COVER FOR YOUR WORKING DAY
Self-employed van insurance
Your van is part of your working day. Explore van insurance for sole traders and self-employed workers, with the right use, drivers and cover details for a MYB quote.
Get a quoteTell us about your business and our team will contact you to discuss a quote.
A CLEAR STARTING POINT
What is self-employed van insurance?
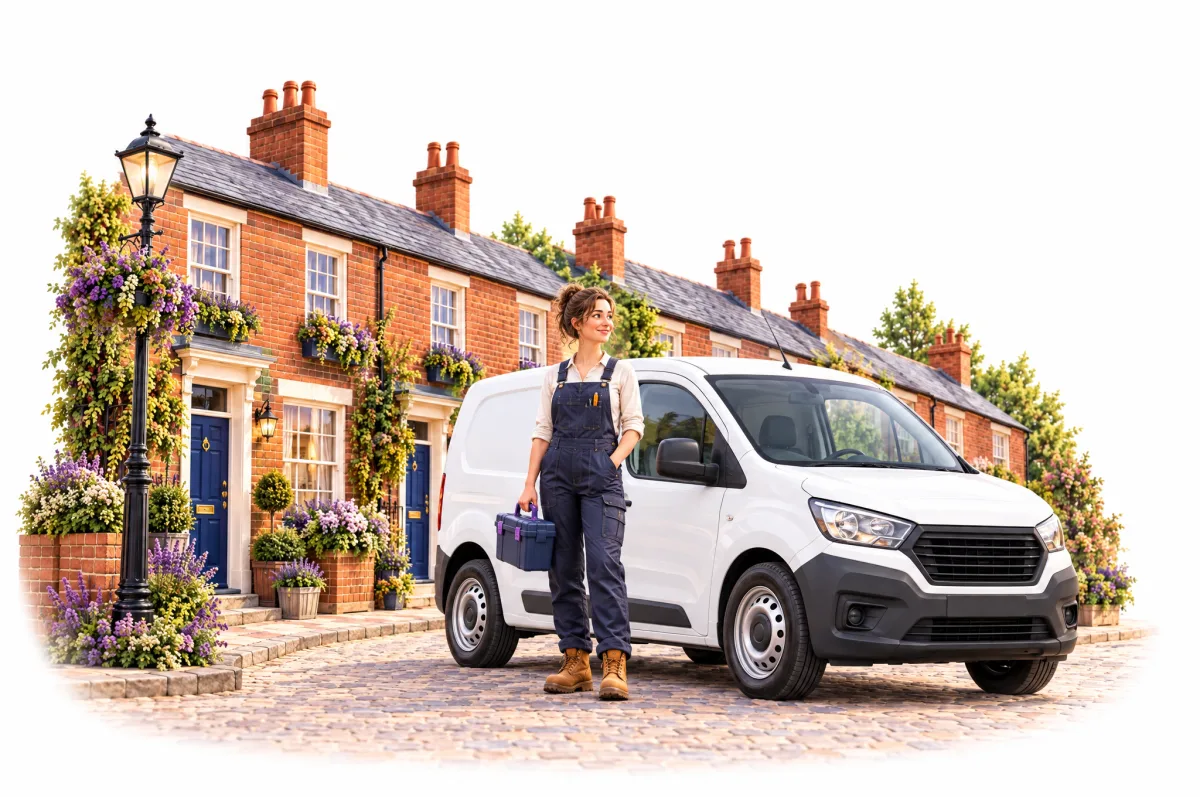
Being self-employed does not create a separate class of motor insurance. Your policy needs to reflect how you use the van, who owns and drives it, and the work you carry out. A tradesperson carrying tools has different needs from someone delivering goods for payment.
THE DETAILS THAT MATTER
Match the policy to your working day
Explain where you travel, what you carry and whether customers pay you to transport goods. Include occasional activities as well as your main trade. If you change from visiting sites to making paid deliveries, tell the insurer before the change rather than assuming the existing use still fits.
THE DETAILS THAT MATTER
Get the ownership and main driver right
Give accurate details of the policyholder, registered keeper, owner and person who uses the van most. If a finance or lease company owns it, explain that arrangement. Do not list someone else as the main driver to try to reduce the price when you are its main user.
THE DETAILS THAT MATTER
Separate the van from the business risks
Motor insurance does not automatically provide public liability for your work at a customer's property. Tools, goods in transit and liability are separate questions. You can discuss the covers you need together with MYB, but check the insurer and documents for each policy rather than assuming one policy includes everything.
THE DETAILS THAT MATTER
Plan for time without the van
If you cannot work without a suitable van, compare breakdown and replacement-vehicle options carefully. A small courtesy car may not carry your equipment, and replacement vehicles may depend on the cause of the claim or use of an approved repairer. Ask what is included before choosing extras.
PREPARE FOR YOUR QUOTE
The details to have ready.
Start with the enquiry form. These details will help when our team discusses the quote with you.
STRAIGHT ANSWERS
Self-employed van insurance FAQs
Do sole traders need business van insurance?
You need a policy that permits your actual use. If the van is used for your work, disclose that use when arranging cover. Being a sole trader does not make a private-use policy suitable for business journeys.
Can I insure a leased van as a self-employed person?
Tell the insurer about the lease, owner and registered keeper and check the lease company's insurance requirements. Whether cover is available depends on the vehicle, use and insurer.
Can I include my trade insurance in the enquiry?
Yes. The MYB form lets you select van insurance alongside business covers such as public liability and tools. Our team can discuss the requirements; the quote documents will explain whether separate policies are involved.
Will self-employed van insurance cover delivery work?
Not merely because the policy allows business use. Declare paid deliveries and the type of goods carried. Courier, haulage or food-delivery work can need different terms or specialist cover.
KEEP YOUR BUSINESS MOVING
More help with your cover.
Business van cover explained
EXPLORE YOUR OPTIONSInsurance for your trade
EXPLORE YOUR OPTIONSTools and equipment cover
Further information: GOV.UK: vehicle insurance requirements and insurance when driving abroad.
Ready to discuss your cover?
Get a quoteAn enquiry does not put cover in place. Insurer acceptance, policy terms, limits and excesses apply.